Knowing the value of your home is essential in many people’s eyes when they are considering making a purchase or selling. There are two widely used methods for estimating a property value: Comparative Market Analysis (CMA) and professional appraisal.
Knowing what the difference between a CMA vs appraisal is can help you know which method is appropriate to you when you’re getting ready to list, you’re putting in an offer, or getting a mortgage.
What is a Comparative Market Analysis?
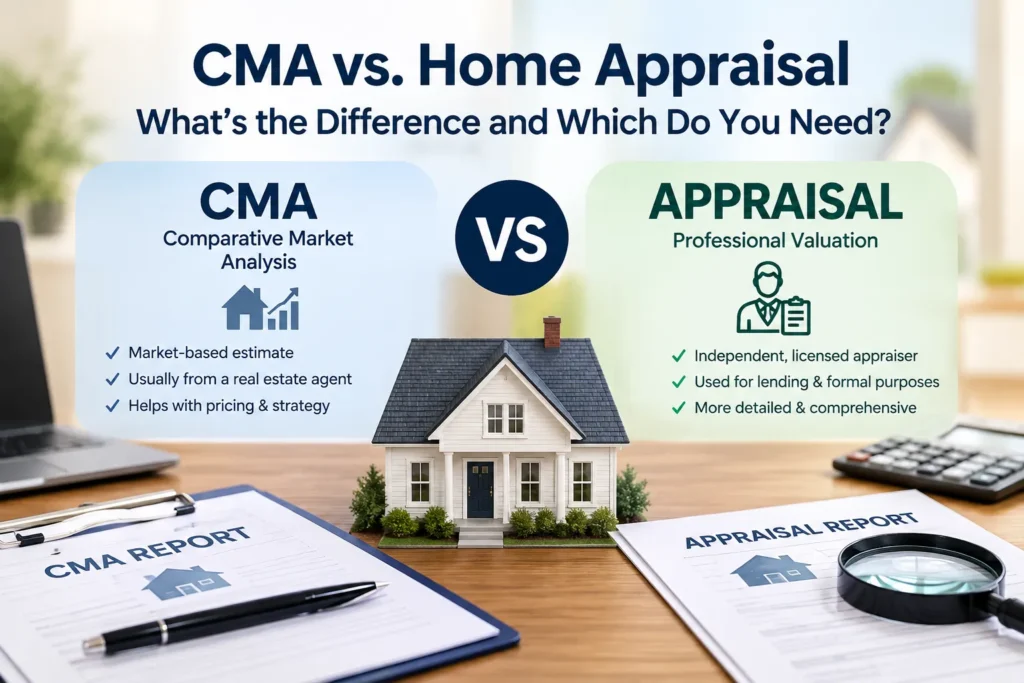
A comparative market analysis is an estimate of a home’s likely market value based on recently sold properties that are similar to it. A CMA is usually a real estate agent’s guide to home valuation, which takes into account location, size, condition, features, and recent sales.
A CMA can assist buyers in determining if the asking price of a property is reasonable, and sellers in deciding on the price of a property. It is not the same as a formal property appraisal as it is based on market data and an agent’s analysis.
What is a Property Appraisal?
Property appraisal is the opinion of the value of a property given by a trained professional. The appraiser assesses the property’s features, comparable sales and other market factors that may affect the property value.
Appraisals are usually a part of the mortgage process and lenders will require one as part of the criteria for approving some of their loans.
In contrast to a CMA, an appraisal is a professional appraisal that is done for a particular purpose.
CMA vs Appraisal: What is the Difference?
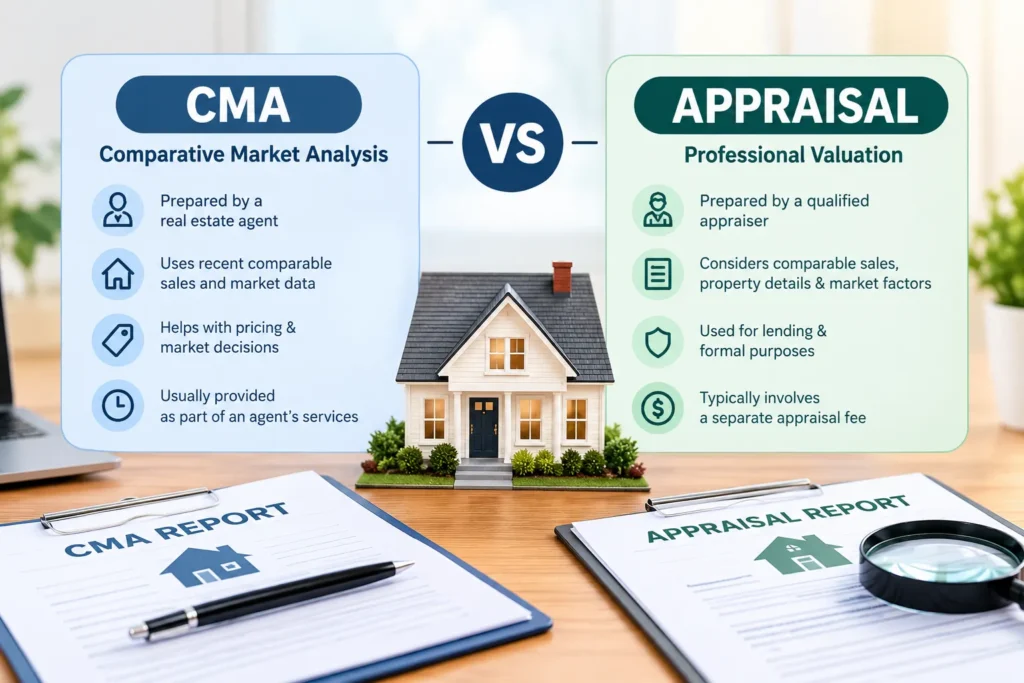
The main difference in CMA vs appraisal is who prepares the valuation and how it is used.
| CMA | Home Appraisal |
| Usually prepared by a real estate agent | Prepared by a qualified appraiser |
| Primarily helps with pricing and market decisions | Often used for lending and other formal purposes |
| Uses comparable local sales and market information | Considers comparable sales, property characteristics, and other valuation factors |
| Usually provided as part of an agent’s services | Typically involves a separate appraisal fee |
| Not generally a formal lending valuation | Commonly required by mortgage lenders |
CMA vs Appraisal: Are They the Same Thing?
A CMA gives an estimate of value based on the market, and an appraisal is a professional opinion of value that is independent from the market.
A seller might ask for a CMA prior to putting their home on the market, to find out what the market is worth. Once an offer is accepted, a home buyer’s lender may want an appraisal as part of the mortgage application process.
When Do You Need a CMA?
A CMA can be useful when you’re:
- Preparing to sell your home
- Deciding on a listing price
- Considering whether to adjust an asking price
- Evaluating comparable homes before making an offer
- Reviewing current local market conditions
A CMA can be a valuable tool for sellers as a starting point for pricing. It can also be used to shed light on how homes in a similar community might have varying prices depending on conditions, updates, location, and other factors.
When Do You Need an Appraisal?
A formal valuation is more likely to require an appraisal. Appraisals are often requested by mortgage lenders to ascertain if the home is a good collateral for the mortgage.
Depending on the situation, an appraisal can also apply to some estate, tax, divorce, refinancing or other financial situations.
If a lender has a specific requirement for an appraisal, a CMA will not be acceptable.
Which One Should You Get?
It depends on the purpose you want to achieve. A CMA might be helpful if you’re primarily looking to understand the market and to find a fair listing or offer price.
In general, if you are having a mortgage appraised or appraising a home for another reason where an independent valuation of the home is needed, then you will require a professional appraisal.
Comparative market analysis vs appraisal is not as much a decision of which to choose, as it is an understanding of what they are used for.
Conclusion:
When it comes to an important real estate decision, it is important to understand the difference between cma vs appraisal. A CMA is about the market and similar properties, whereas an appraisal offers an independent view of the value of a property for a specific purpose.
When buying, selling, refinancing or just doing research into your property’s value, knowing how each process works will be beneficial when deciding on a real estate decision.
Frequently Asked Questions
What is the difference between a cma vs appraisal?
A CMA is typically prepared by a real estate agent to estimate market value, while an appraisal is prepared by a qualified appraiser for a formal valuation purpose.
Is a CMA the same as an appraisal?
No. Although both consider comparable properties and market information, they are different valuation products with different purposes.
What does CMA stand for in real estate?
CMA stands for Comparative Market Analysis. It uses recent sales and other market information to estimate what a property may reasonably sell for.
Can a CMA determine property value?
A CMA can provide an estimate of market value based on comparable sales, but it is not a formal appraisal.
Does a lender accept a CMA instead of an appraisal?
Generally, if a lender requires an appraisal, a CMA does not replace the required professional appraisal.
Who prepares a property appraisal?
A property appraisal is prepared by a qualified appraiser who evaluates the property and relevant market information to develop an opinion of value.
When should a seller get a CMA?
Sellers often request a CMA before listing their property to help establish a reasonable asking price based on recent comparable sales and current market conditions.
Is an appraisal required when buying a house?
Mortgage lenders commonly require an appraisal, although requirements can vary depending on the loan type, lender, and circumstances.
What factors affect a CMA?
A CMA can consider recent comparable sales, location, property size, condition, upgrades, features, and current market conditions.
Should I get a CMA or appraisal?
If you need pricing guidance for buying or selling, a CMA may be useful. If you need a formal independent valuation for lending or another specific purpose, an appraisal may be appropriate.